In this article
Introduction & Regulatory Context
The landscape of Goods and Services Tax (GST) compliance in India has undergone a significant transformation with the Central Board of Indirect Taxes and Customs (CBIC) introducing comprehensive amendments to the Central Goods and Services Tax (CGST) Rules, 2017. These pivotal changes, primarily brought into effect through Notification No. 05/2026–Central Tax, dated October 26, 2026, mark a decisive shift towards automated enforcement, digital integration, and real-time scrutiny. While most provisions became effective on November 1, 2026, other parts are slated for phased implementation up to April 1, 2027.
This overhaul impacts every GST-registered business, taxpayer, and GST practitioner across India, including the vibrant business community in Pune and Maharashtra. The new framework demands a proactive and vigilant approach to compliance, moving away from traditional reactive methods. Businesses must now align their internal processes with the GST portal's enhanced capabilities, which leverage artificial intelligence and automated data triangulation to monitor compliance continuously.
Key Amendments & Their Immediate Impact
The latest amendments introduce several critical changes that necessitate immediate attention and adaptation:
Automated GSTIN Suspensions & Cancellations
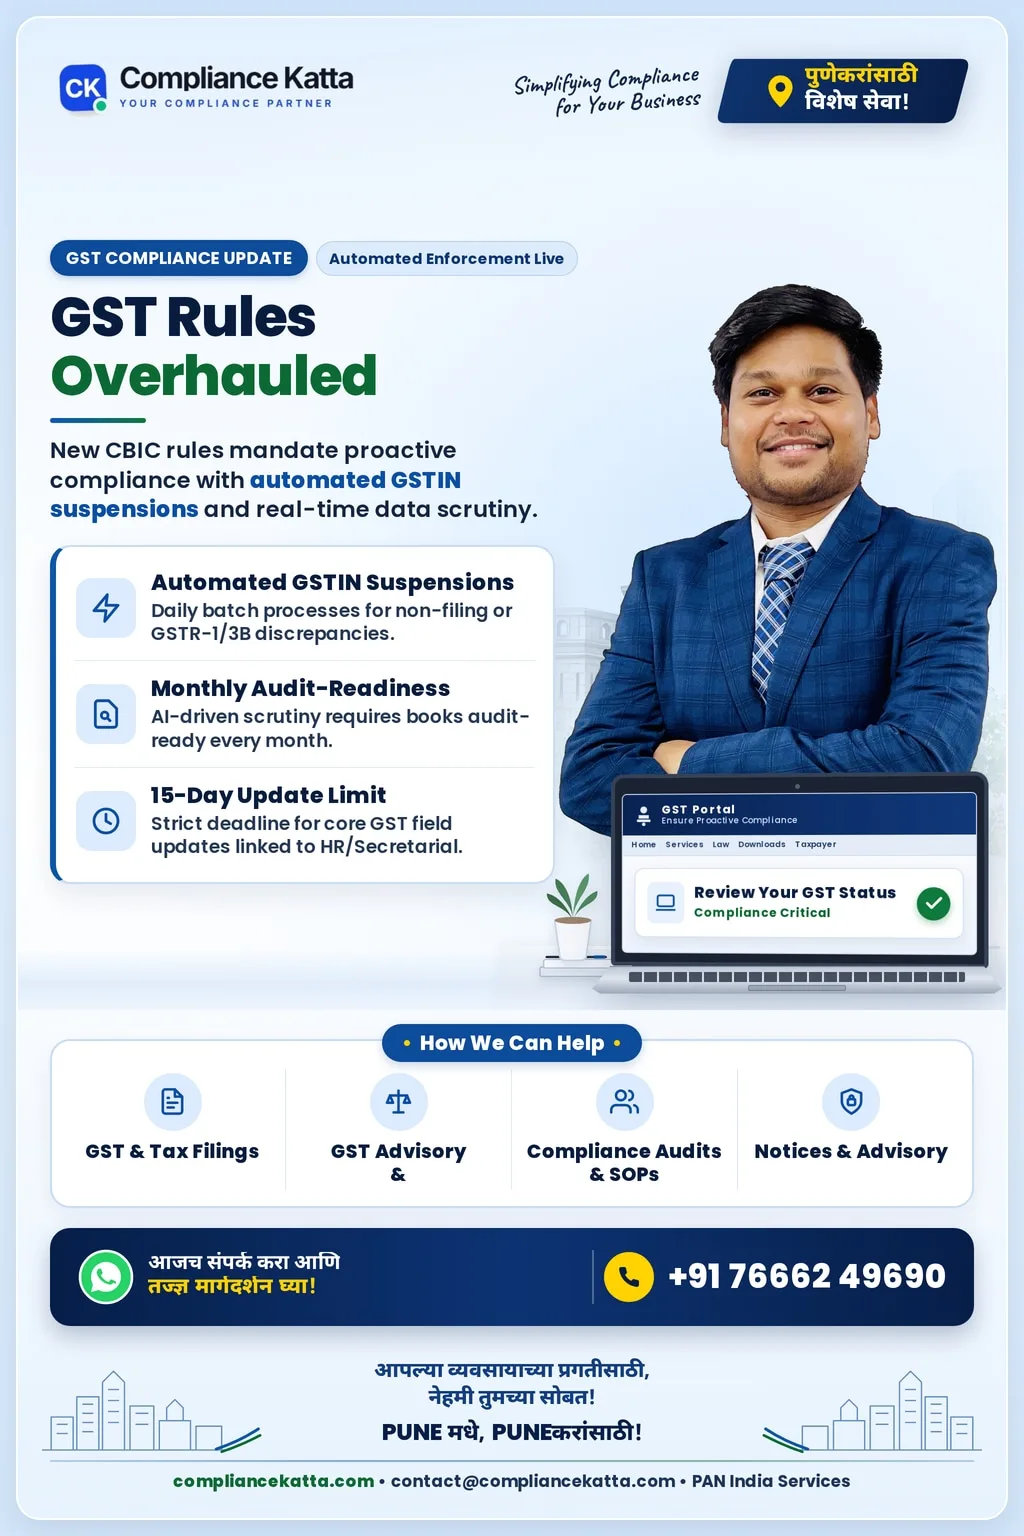
One of the most impactful changes is the implementation of daily automated batch processes for the suspension and cancellation of GSTINs under Rules 21A and 22 of the CGST Rules. This automated action is no longer a manual intervention but a systemic response triggered by specific non-compliance events. Taxpayers failing to file returns for six consecutive months, or those exhibiting substantial discrepancies between their GSTR-1 (outward supplies) liability and GSTR-3B (tax payment), will face swift and automated suspension of their GSTIN. This mechanism aims to streamline enforcement and ensure timely compliance.
Mandatory Monthly Audit-Readiness
The CBIC's integration of artificial intelligence and automated data triangulation capabilities means that businesses' compliance is under constant, real-time scrutiny. Consequently, it is now mandatory for businesses to ensure their books of accounts are audit-ready on a monthly basis. This proactive measure is crucial for identifying and rectifying discrepancies promptly, preventing potential triggers for automated actions, and maintaining a clean compliance record. The era of preparing for audits annually is over; continuous audit-readiness is the new norm.
Strict 15-Day Limit for Core GST Field Updates
Another significant amendment introduces a stringent 15-day limit for updating core GST fields. This change mandates that companies directly link Secretarial or Human Resources (HR) changes to the Tax department and promptly update relevant GST information. This eliminates the previous practice of accumulating changes and addressing them during year-end reviews. Any change in business constitution, address, contact details, or other core registration particulars must be reflected on the GST portal within this strict timeframe, ensuring that the tax authorities always have access to accurate and up-to-date information.
Strategic Shift: From Reactive to Proactive Compliance
These amendments collectively signal a fundamental shift in the philosophy of GST compliance – from reactive problem-solving to proactive prevention. The emphasis is now on continuous adherence and real-time data accuracy.
Redesigning Standard Operating Procedures (SOPs)
To navigate this new framework effectively, businesses must critically review and redesign their internal Standard Operating Procedures (SOPs). Existing SOPs, which might have been adequate for a more manual and reactive compliance environment, are now insufficient. New SOPs must incorporate daily/weekly reconciliation checks, monthly audit-readiness protocols, and a robust system for timely updates of core GST fields. This redesign is crucial for aligning internal operations with the automated enforcement and digital data triangulation capabilities of the GST system, ensuring continuous adherence to GST regulations and mitigating risks of automated penalties.
Key Changes at a Glance
| Aspect | Previous Approach (Implied) | New Requirement (w.e.f. Nov 1, 2026) | Impact on Businesses |
|---|---|---|---|
| GSTIN Suspension | Often manual intervention, delayed action for non-filing/discrepancies. | Automated daily batch processes for suspension/cancellation if 6-month non-filing or GSTR-1/3B discrepancies. | Immediate risk of GSTIN suspension, disruption of business operations, and supply chain. |
| Audit Readiness | Primarily annual or on-demand preparation for audits. | Mandatory monthly audit-readiness due to AI/automated data triangulation and real-time scrutiny. | Requires continuous, rigorous internal accounting and reconciliation processes. |
| Core GST Field Updates | Updates often delayed, sometimes consolidated for year-end reviews. | Strict 15-day limit for updating core GST fields (e.g., address, directorship) linked to Secretarial/HR changes. | Demands immediate internal communication and prompt action for any administrative changes. |
| Compliance Strategy | Often reactive, addressing issues as they arise or during periodic reviews. | Proactive redesign of SOPs to align with automated enforcement and digital data triangulation. | Necessitates a fundamental shift to continuous monitoring and preventive compliance. |
Expert Advice from Compliance Katta:"The new CGST Rules demand a paradigm shift in how businesses approach GST compliance. Proactive monitoring, real-time data reconciliation, and robust internal controls are no longer optional but essential for survival. Businesses in Pune and across India must invest in technology and training to adapt swiftly, ensuring their systems are integrated and their teams are well-versed in the new automated enforcement mechanisms. Compliance Katta strongly advises a comprehensive review of all GST-related processes immediately."
Practical Compliance Checklist for Businesses
To ensure seamless compliance with the updated CGST Rules, consider the following actionable steps:
- Daily/Weekly Data Reconciliation: Implement robust systems for daily or weekly reconciliation of GSTR-1 (outward supplies) with GSTR-3B (tax payments) and GSTR-2A/2B (input tax credit). This is critical to avoid discrepancies that trigger automated GSTIN suspension.
- Monthly Audit-Readiness Protocol: Establish a routine for preparing and reviewing books of accounts on a monthly basis, ensuring they are audit-ready. This includes verifying all transactions, invoices, and ledgers against GST filings.
- 15-Day Update Mechanism: Create a strict internal protocol to update core GST registration fields within 15 days of any Secretarial or HR changes (e.g., change in address, directorship, contact details). Integrate this with your HR/Admin departments.
- SOP Redesign & Training: Conduct a thorough review and redesign of all GST-related Standard Operating Procedures (SOPs). Provide comprehensive training to your accounting, finance, and administrative teams on the new rules, automated enforcement triggers, and revised internal processes.
- Leverage Technology: Utilize accounting software and GST compliance tools that offer real-time data integration, reconciliation features, and alerts for potential discrepancies.
- Regular Health Checks: Perform periodic internal GST health checks to identify and rectify any compliance gaps before they are flagged by the automated system.
Conclusion & Compliance Katta's Expert View
The amendments to the CGST Rules, 2017, usher in a new era of digital-first, automated GST enforcement. While the primary penalty highlighted is the automated GSTIN suspension and cancellation for non-compliance, it is crucial to remember that non-adherence to GST regulations generally attracts significant fines and legal repercussions under the CGST Act. The majority of these changes became effective on November 1, 2026, demanding immediate action from all GST-registered entities.
For businesses in Pune and across Pan-India, adapting to these changes is not merely a compliance task but a strategic imperative. Proactive engagement with these new rules will safeguard your business from disruptions, penalties, and reputational damage. Compliance Katta is equipped to assist you in navigating this complex regulatory landscape, ensuring your business remains compliant and resilient.
Disclaimer: This update is for general informational and educational purposes only and does not constitute formal legal, tax, or professional advice. Applicability may vary based on specific facts, turnover thresholds, and subsequent notifications. Please consult a qualified professional before acting on this information. For Pune & pan-India compliance assistance, contact Compliance Katta on WhatsApp at +91 76662 49690.
Common Questions
Q.What specific triggers lead to automated GSTIN suspension under the new rules?
Automated GSTIN suspension is triggered if a taxpayer fails to file their GST returns for six consecutive months. Additionally, substantial discrepancies identified between the GSTR-1 (outward supplies) liability and GSTR-3B (tax payment) can also lead to automated suspension and potential cancellation under Rules 21A and 22 of the CGST Rules.
Q.What does "mandatory monthly audit-readiness" mean for my business operations?
It means your business must ensure its books of accounts, including ledgers, invoices, and transaction records, are prepared and reconciled to an audit-ready standard every month. This is due to the CBIC's use of AI and automated data triangulation for real-time compliance scrutiny, requiring continuous accuracy and immediate rectification of any identified discrepancies.
Q.Which "core GST fields" are subject to the new 15-day update limit?
Core GST fields typically include critical registration details such as the principal place of business address, additional places of business, details of partners/directors/proprietors, contact information, and changes in business constitution. Any Secretarial or HR changes impacting these fields must now be updated on the GST portal within a stringent 15-day timeframe.
Q.How should businesses redesign their Standard Operating Procedures (SOPs) to comply with these amendments?
Businesses should redesign their SOPs to embed proactive compliance measures. This includes implementing daily/weekly GSTR-1 and GSTR-3B reconciliation, establishing monthly internal audit checks, creating a strict 15-day protocol for updating core GST fields, and ensuring continuous training for staff on the new automated enforcement mechanisms and digital data triangulation.
Q.What are the general consequences of a GSTIN suspension, even if specific penalty figures aren't detailed?
A GSTIN suspension can severely disrupt business operations. It typically means the taxpayer cannot file returns, issue taxable invoices, or claim Input Tax Credit (ITC). This can lead to a halt in business transactions, inability to collect GST from customers, and significant financial and legal repercussions, including potential cancellation of registration and further penalties under the CGST Act.