In this article
Introduction & Regulatory Context
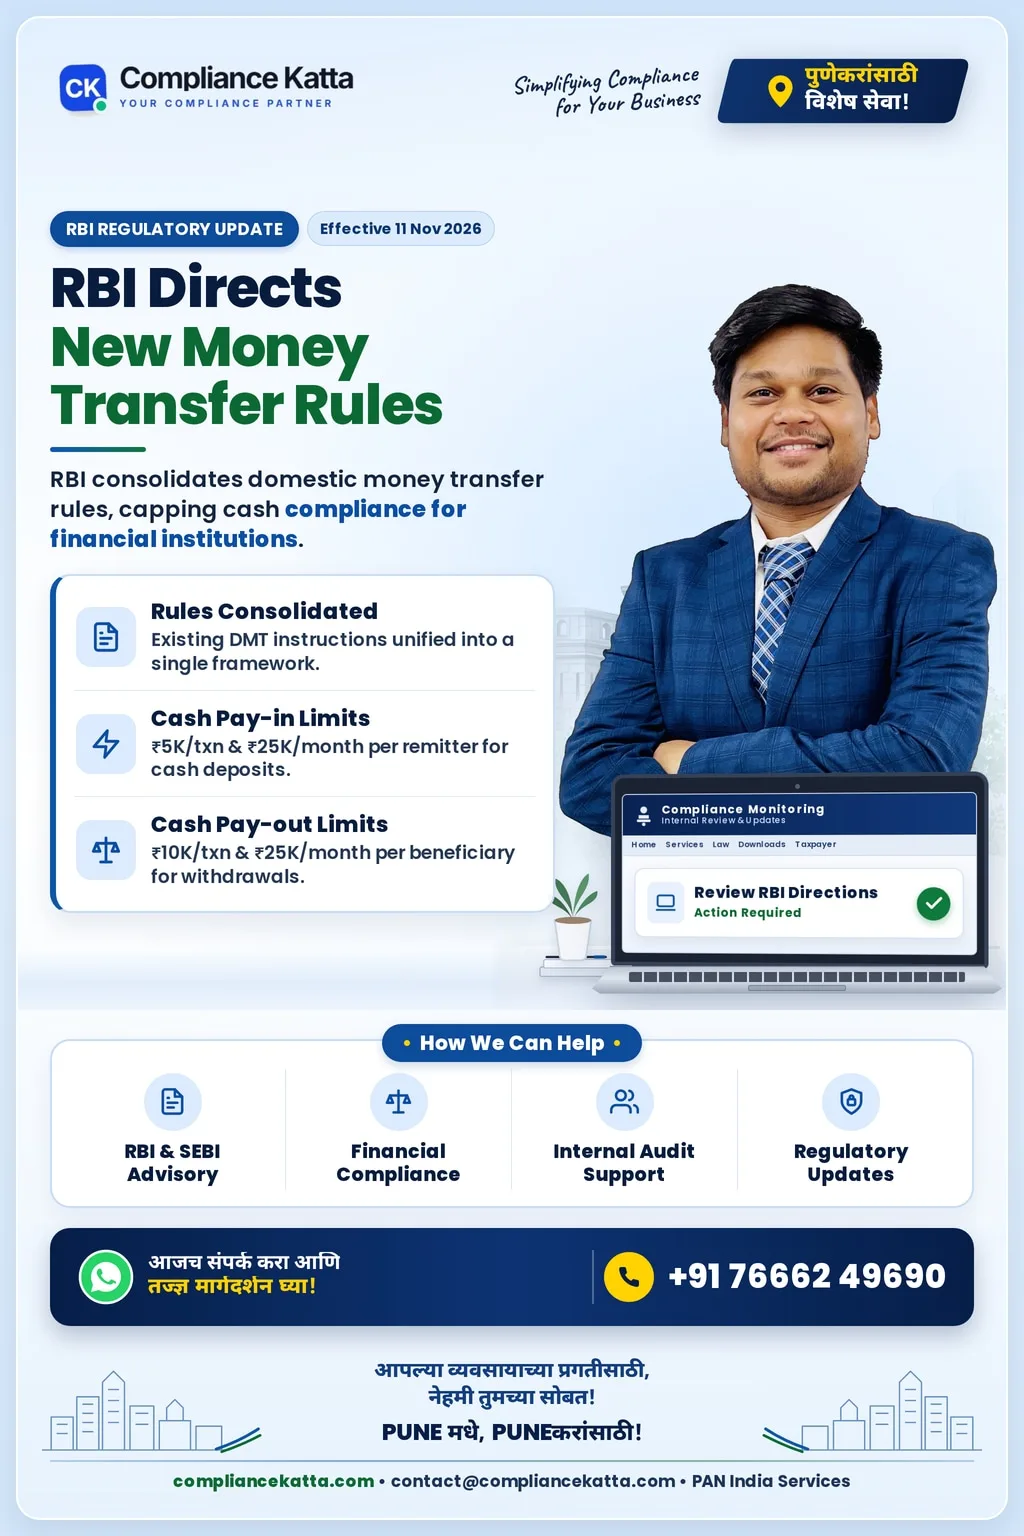
The Reserve Bank of India (RBI) continues its commitment to strengthening the financial ecosystem and ensuring robust regulatory oversight. In a significant move, the RBI has issued the Reserve Bank of India (Domestic Money Transfer) Directions, 2026, effective immediately from November 11, 2026. These new directions are a crucial step towards consolidating and streamlining the framework for domestic money transfers (DMT) across India, impacting a wide array of financial institutions and individuals involved in cash-based transactions.
This consolidation aims to bring greater clarity, enhance security, and standardize operational procedures for domestic money transfers conducted through formal banking channels. For businesses and individuals in Pune and across Pan-India, understanding these updated regulations is paramount to ensure seamless compliance and avoid potential disruptions in financial operations.
Key Highlights & Statutory Changes
The new RBI Directions introduce several pivotal changes and consolidate existing instructions into a single, comprehensive document. These changes are designed to improve the integrity of the domestic money transfer system and mitigate risks associated with cash transactions.
Consolidation of Rules
One of the primary objectives of these directions is the consolidation of all existing instructions governing domestic money transfers. This move simplifies the regulatory landscape, making it easier for financial institutions to adhere to a unified set of guidelines rather than navigating disparate circulars and notifications.
Revised Cash Transaction Limits
The directions introduce specific caps on cash pay-ins and pay-outs, directly impacting how individuals send and receive money:
- Cash Pay-in Limits: For cash deposits made through agents or ATMs, a cap of ₹5,000 per transaction and ₹25,000 per month per remitter has been imposed.
- Cash Pay-out Limits: For cash withdrawals or pay-outs from bank accounts, the limits are set at ₹10,000 per transaction and ₹25,000 per beneficiary per month.
Enhanced Security and Monitoring
To bolster the security of domestic money transfers, the RBI has mandated an additional authentication step for every transfer. Furthermore, banks are now required to significantly strengthen their monitoring mechanisms to detect and report unusual fund transfer activities, thereby curbing potential misuse.
Grievance Redressal Mechanism
Customer complaints arising from these transactions will now be brought under the ambit of the RBI's Integrated Ombudsman Scheme, 2026. This provides a structured and accessible channel for individuals to seek redressal for any issues encountered during domestic money transfers.
Applicability & Impact Analysis
The Reserve Bank of India (Domestic Money Transfer) Directions, 2026, have a broad scope of applicability, ensuring comprehensive coverage of the formal financial sector involved in money transfers. These directions apply to:
- Scheduled Commercial Banks (including Regional Rural Banks)
- Urban Co-operative Banks
- State Co-operative Banks
- District Central Co-operative Banks
- Authorised Payment System Operators and Participants (both banks and non-banks)
Beyond financial institutions, these directions directly impact individuals who frequently use cash for sending or receiving money domestically. Businesses, especially those dealing with cash transactions or facilitating payments, must also understand these limits to ensure their operational compliance.
Here's a comparative summary of the key provisions:
| Feature | Previous Framework (Fragmented) | New Directions (RBI DMT Directions, 2026) |
|---|---|---|
| Regulatory Framework | Multiple instructions/circulars | Consolidated into a single document |
| Cash Pay-in Limit (Per Transaction) | Varied/Unspecified | ₹5,000 |
| Cash Pay-in Limit (Per Month, Per Remitter) | Varied/Unspecified | ₹25,000 |
| Cash Pay-out Limit (Per Transaction) | Varied/Unspecified | ₹10,000 |
| Cash Pay-out Limit (Per Month, Per Beneficiary) | Varied/Unspecified | ₹25,000 |
| Security Measures | Standard protocols | Additional authentication step; strengthened monitoring of unusual activities |
| Grievance Redressal | Existing bank/PSO mechanisms | RBI's Integrated Ombudsman Scheme, 2026 |
Practical Compliance Checklist for Financial Institutions & Businesses
Given the immediate effectiveness of these directions from November 11, 2026, financial institutions and businesses must take prompt action to ensure compliance. Compliance Katta advises the following:
- Review Internal Policies: Immediately update internal policies and operational procedures to align with the new cash pay-in and pay-out limits.
- System Upgrades: Ensure that all IT systems, including agent interfaces and ATM software, are configured to enforce the new transaction limits and incorporate the additional authentication step.
- Staff Training: Conduct comprehensive training for all relevant staff, especially those at agent locations and customer service desks, on the new directions, limits, and grievance redressal process.
- Customer Communication: Clearly communicate the new limits and security requirements to customers through various channels (website, notices, SMS, etc.) to manage expectations and ensure smooth transactions.
- Monitoring Enhancements: Strengthen fraud detection and transaction monitoring systems to identify and flag unusual or suspicious fund transfer activities as mandated by the RBI.
- Grievance Redressal Integration: Ensure that customer complaint handling processes are integrated with the RBI's Integrated Ombudsman Scheme, 2026, and that staff are aware of the new redressal pathway.
Expert Advice from Compliance Katta:For financial institutions and businesses in Pune and across Pan-India, proactive compliance with these new RBI directions is not merely a regulatory obligation but a strategic imperative. Non-adherence can lead to significant regulatory scrutiny and penalties. We recommend a thorough internal audit of your domestic money transfer processes and systems to identify any gaps and implement necessary changes without delay. Our team at Compliance Katta specializes in navigating complex financial regulations and can assist you in developing robust compliance frameworks tailored to these new requirements.
Conclusion
The Reserve Bank of India (Domestic Money Transfer) Directions, 2026, mark a significant evolution in the regulatory landscape for domestic money transfers. By consolidating rules, imposing clear transaction limits, and enhancing security measures, the RBI aims to foster a more secure and transparent financial environment. All impacted entities, from large scheduled banks to local co-operative banks and payment system operators, must prioritize immediate implementation of these directions. Individuals, too, should be aware of these changes to plan their cash-based transactions accordingly.
Disclaimer: This update is for general informational and educational purposes only and does not constitute formal legal, tax, or professional advice. Applicability may vary based on specific facts, turnover thresholds, and subsequent notifications. Please consult a qualified professional before acting on this information. For Pune & pan-India compliance assistance, contact Compliance Katta on WhatsApp at +91 76662 49690.
Common Questions
Q.What are the new cash pay-in limits for domestic money transfers?
Under the RBI (Domestic Money Transfer) Directions, 2026, cash pay-ins through agents or ATMs are now capped at ₹5,000 per transaction and ₹25,000 per month per remitter. This applies to all scheduled commercial banks, co-operative banks, and authorized payment system operators.
Q.What are the new cash pay-out limits for domestic money transfers?
The new directions cap cash pay-out transfers from bank accounts at ₹10,000 per transaction and ₹25,000 per beneficiary per month. Financial institutions must ensure their systems and processes enforce these new limits effectively.
Q.Who is impacted by these new RBI Domestic Money Transfer Directions?
These directions apply to scheduled commercial banks (including regional rural banks), urban co-operative banks, state co-operative banks, district central co-operative banks, and authorised payment system operators and participants (both banks and non-banks). They also directly impact individuals who send or receive cash-based domestic money transfers.
Q.What new security measures have been introduced?
The RBI mandates an additional authentication step for every domestic money transfer. Furthermore, banks are required to strengthen their monitoring of unusual fund transfer activities to enhance security and prevent fraudulent transactions.
Q.What is the grievance redressal mechanism for issues related to these transactions?
Customer complaints arising from domestic money transfer transactions under these new directions will now fall under the purview of the RBI's Integrated Ombudsman Scheme, 2026. This provides a unified and accessible platform for customers to address their grievances.